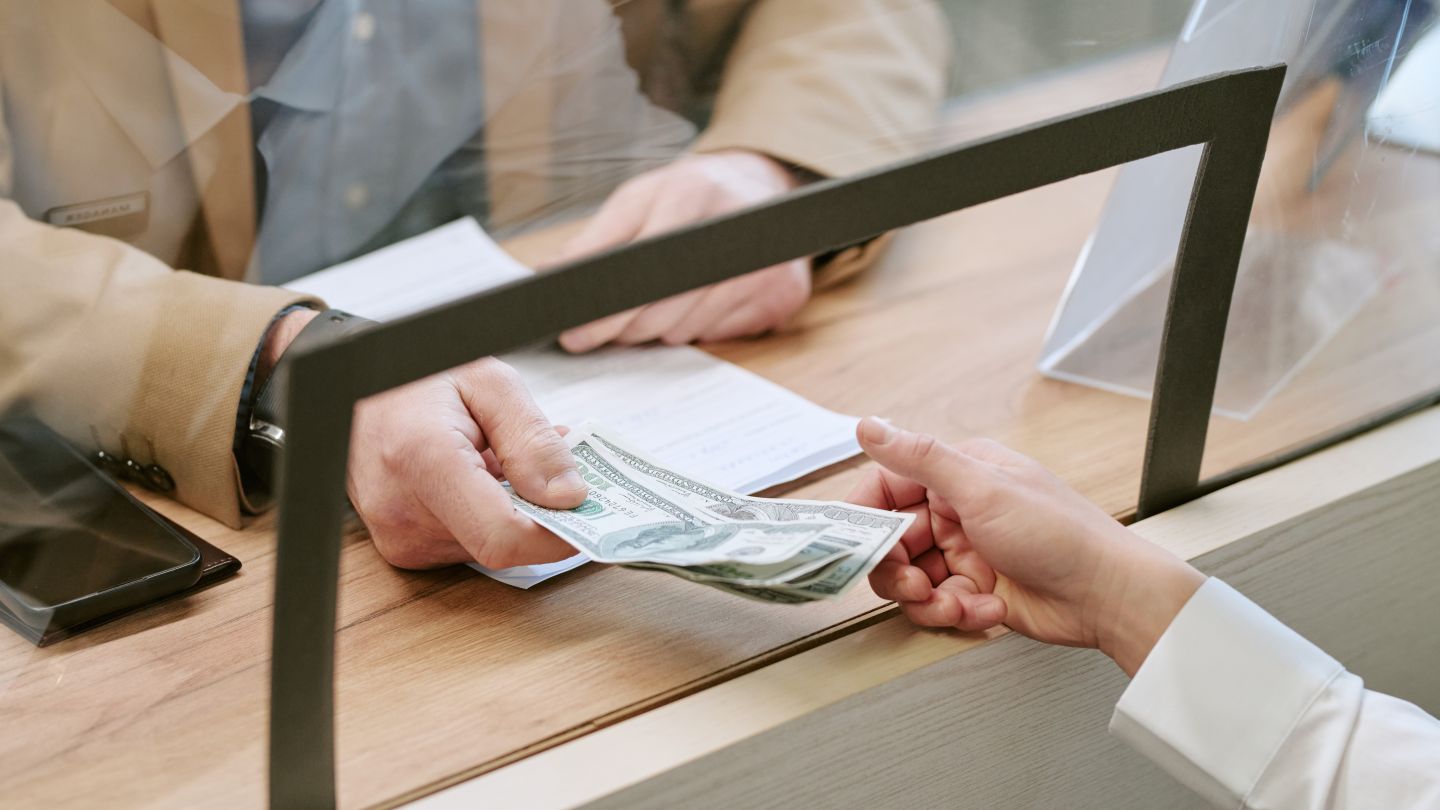
British banks could face new limits on further branch closures after the UK government pledged legislation to safeguard “face-to-face banking”.
HM Treasury agreed to implement the headline proposal of an independent assessment, which advised establishing a statutory duty for major retail banks to “ensure reasonable access to essential in-person banking services”.
Access deeper industry intelligence
Experience unmatched clarity with a single platform that combines unique data, AI, and human expertise.
The impending mandate effectively establishes a baseline for branch networks across the UK.
High street lenders currently maintain roughly 4,000 operational sites, down from approximately 19,000 in the 1980s following 15,000 shutdowns.
The study established that “harm is material and recurring” across an estimated 3mn regular users of counter services, encompassing elderly, disabled, severely ill, and mentally ill individuals.
“Some people told us they had spent the best part of a day getting access to in-person banking services,” Richard Lloyd, the report’s author, told the FT.
“A lot of people are just giving up doing the banking they need to do.”
Lloyd, formerly the chief executive of Which?, noted that commercial operators in North-West England reported that they “felt they did not have access to the ability to talk privately with someone about their banking services” amidst widespread local shutdowns.
Drawing on upwards of 18,000 public submissions, the inquiry highlighted “widespread poor customer outcomes that can be directly attributed to the decline in access to in-person services”.
Ministers must still decide the criteria defining “larger providers of personal current accounts” subject to the statutory baseline, as Lloyd left the regulatory scope open.
Consequently, Whitehall must resolve whether app-based providers such as Revolut and Monzo must help fund shared banking hubs established in areas without commercial bank branches.
Traditional financial institutions have funded 250 shared banking hubs to date. Managed via the Post Office and Cash Access UK, these sites facilitate cash transactions for customers of leading banks and building societies.
The Treasury plans to finalise the operational standards alongside the Financial Conduct Authority, commercial lenders, and consumer advocacy organisations.