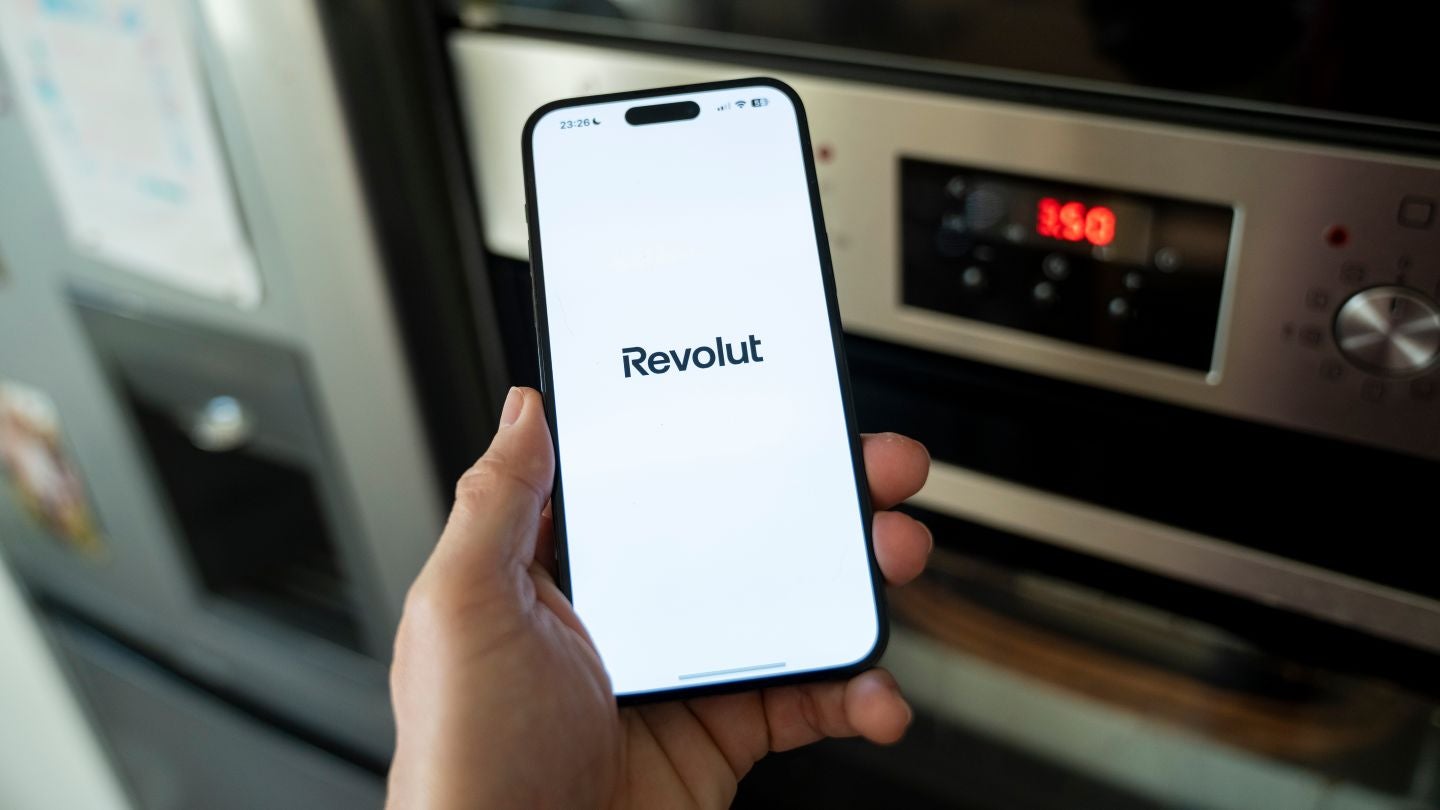
Revolut is weighing a dual stock market listing in New York and London, chief executive and founder Nik Storonsky told Les Echos, backing up earlier media reports.
Discussing the company’s flotation plans, Storonsky said the US remained the preferred market because of its deeper investor base, but said the group was currently looking at a dual listing on Nasdaq and the London Stock Exchange.
Go deeper with GlobalData
Access deeper industry intelligence
Experience unmatched clarity with a single platform that combines unique data, AI, and human expertise.
“Yes, “because it’s a larger market. It includes institutional investors, hedge funds, fund managers, and a considerable number of individual investors”.
“So we have the choice between selling in a small market with few buyers, or in a gigantic market with a huge number of buyers who will compete fiercely for our shares. Therefore, yes, we prefer the United States”.”
He added: “In reality, we are currently planning a dual listing, on the London Stock Exchange and the Nasdaq.”
In the interview, Storonsky said that five years ago many investors questioned whether Revolut could reproduce in Europe the growth it had achieved in the UK, and whether it would secure banking licences.
He said those doubts had since been answered.
He added traditional banks had responded to Revolut by cutting charges, broadening their product ranges and improving services, with many now trying to replicate its products.
On France, Storonsky said the banking licence obtained there would enable Revolut to roll out new regulated products including credit cards, loans and, potentially, mortgage lending, as well as access to some tax-advantaged products.
He said France was selected as Revolut’s Western European base because of its regulators, which he described as highly regarded and pragmatic.
Storonsky outlined the company had been late in applying for banking licences, adding that it was simpler to obtain one for a bank with no customers than for one serving tens of millions, because regulators assess the risks posed to the financial system.
On lending, he said most of Revolut’s income currently came from transaction fees rather than loan margins, and that credit would remain a smaller part of the business.
He noted that if lending expands, the company plans to securitise loans to keep its structure lean and limit credit risk.
Speaking about the US, Storonsky said Revolut had applied for a banking licence and had received pre-approval.
He said the company’s American operation was already profitable and expanding without marketing spending, and that obtaining a banking licence would speed up that process.
Storonsky said Revolut generated about $6bn in revenue and $1.7bn in net income last year. He said figures in 2026 would be higher, and that margins were around 80%.
On profitability per customer, he highlighted Revolut remained behind banks because they issue more credit.
However, he added that “we are far superior to banks because our technological infrastructure is streamlined: we don’t have the thousands of suppliers and third-party providers that banks rely on. We don’t employ as many bankers, and most of our systems are automated”.
Looking ahead, Storonsky said he hoped the company would have several hundred million customers within five years, operate across many markets and rank among the top three in each.
He said the main challenge was regulation, adding that expansion across more markets and products increased complexity and risk, requiring the company to simplify its systems and infrastructure.