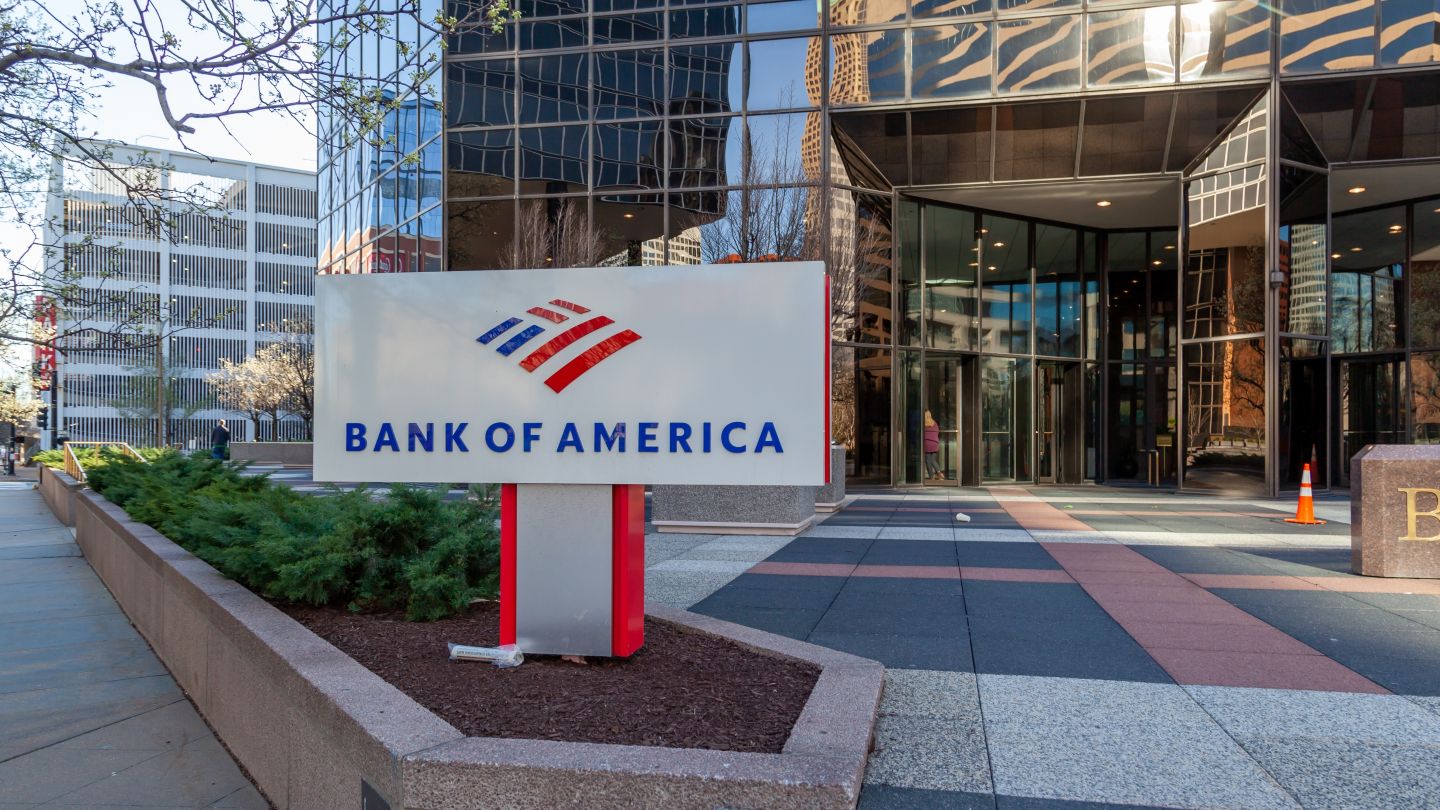
US financial regulators have penalised Bank of America more than $1.21bn across multiple enforcement actions targeting widespread violations of federal sanctions and anti-money laundering (AML) statutes.
The punitive package incorporates the third-largest penalty ever recorded by the US Department of the Treasury, alongside the largest fine ever handed down by the Office of the Comptroller of the Currency (OCC).
Go deeper with GlobalData
Access deeper industry intelligence
Experience unmatched clarity with a single platform that combines unique data, AI, and human expertise.
Responding to inquiries from Retail Banker International, a Bank of America spokesperson said: “Financial crime compliance is serious, and we are responsible for getting it right. We worked with regulators to reach these penalty resolutions stemming from violations cited in the previously reported 2024 OCC Consent Order and FinCEN’s investigation. We have invested billions of dollars in technology and dedicated thousands of employees to combat financial crime, and our team is far along with and committed to completing the work required to address the issues raised by our regulators.”
The $1.2bn non-tax-deductible charge hit the bank’s third quarter performance, lowering earnings per share (EPS) by roughly 17 cents.
FinCEN assessed a $1.2bn penalty after finding that the institution failed to counter and disclose “priority national security risks”, explicitly citing illicit capital flows along the southwest border and Chinese money laundering networks.
In parallel actions, the OCC imposed a $750m civil money penalty over an ineffective and deficient bank secrecy act (BSA)/AML compliance programme, whilst OFAC concluded an $11.6m settlement resolving apparent infractions across several sanctions regimes, including those directed at Iran, Russia, narcotics, and global terrorism.
Secretary Scott Bessent noted that when a bank of this size “fails to meet” its anti-money laundering and sanctions obligations, “the consequences extend far beyond its own walls, exposing the entire U.S. financial system to significant illicit finance risks”.
He added: “Today’s actions send a clear message that even the biggest financial institutions are not above the law.”
Under the terms established with FinCEN, Bank of America conceded that it “willfully violated” the BSA.
The lender admitted non-compliance across three core mandates: maintaining an AML programme that complied with statutory minimums under the BSA and FinCEN regulations; conducting due diligence regarding correspondent accounts held by foreign financial institutions; and filing SARs.
FinCEN uncovered systemic “deficiencies” in how the institution handled customer due diligence (CDD) alongside its protocols for detecting and disclosing “suspicious” activity.
During this timeframe, Bank of America “prioritised its revenues and minimized the impact on its required compliance resources”.
Consequently, Bank of America omitted to submit timely SARs to FinCEN for more than $5bn in suspicious transactions. Over $1bn of these untracked funds involved national security matters and critical illicit finance threats, encompassing fraud patterns, ties to Chinese Money Laundering Networks, and suspected trade-based money laundering connected to the southwest border.
The newly issued Consent Order obliges the bank to hire an external firm to execute a lookback review, which will identify and lodge notifications with FinCEN for all suspicious transfers missed during the breakdown.
Bank of America must also submit to third-party audits evaluating its CDD, foreign correspondent account due diligence, suspicious activity monitoring systems, and the underlying data governance framework supporting its AML infrastructure.
The bank executed millions of dollars in transfers that apparently breached sanctions programmes concerning Russia, Belarus, Iran, Burma, Somalia, narcotics, and global terrorism.